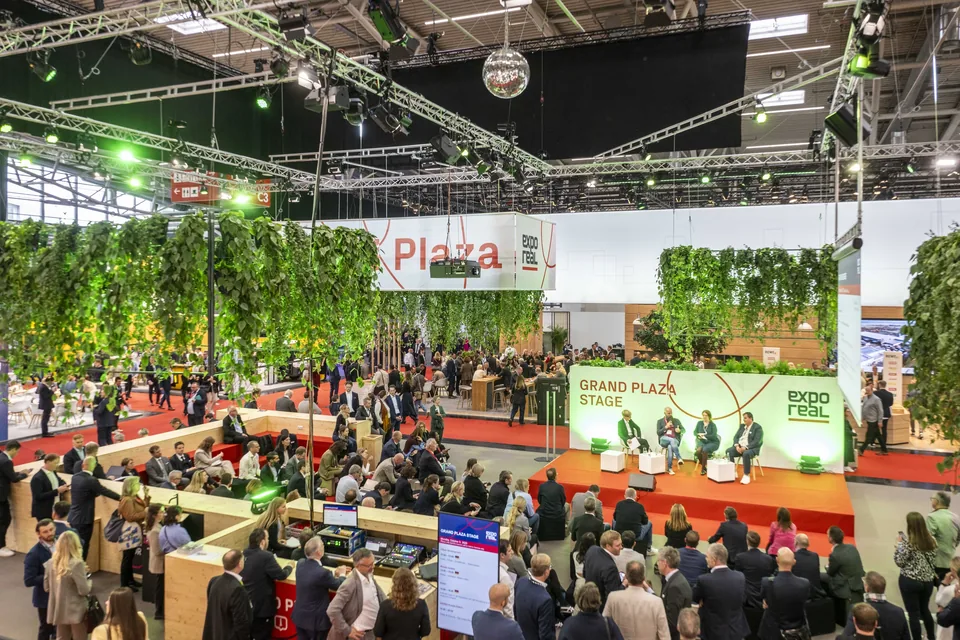
Bid-ask spreads narrowed at EXPO REAL 2024. So did loan-to-values, to a targeted maximum of 55%. Both facts came out of the same client meetings, and they support two different verdicts about the same fair. One reader hears a seller who has finally accepted a lower number and calls it price discovery. Another hears a lender agreeing to extend a loan rather than call a default, and calls it a workout. The session was the same. The transcript would show the same words. What differs is which side of the balance sheet each listener was watching, and that split runs through the entire fair.
The case for calling EXPO REAL a price-discovery room is straightforward. It gathers more of the people who set European property values than almost any other room on the continent, roughly 42,000 participants and 1,742 exhibitors from 34 countries at the 2025 edition, and the 2026 programme opens with an investor panel asking directly whether Europe remains an attractive market. Ahead of the fair, sellers and advisers are saying pricing has stabilised, tying that view to maturing legacy financings, while buyers reply that sellers are now motivated and prices more realistic. Two sides disagreeing about a number, in public, days before meeting in the same halls, is what price discovery looks like from the outside.
The case for calling it a refinancing clinic uses the same source material read for its debt content instead of its price content. CBRE Investment Management's account of the 2024 edition, drawn from client meetings held at the fair, reported a targeted maximum loan-to-value of 55% after repricing, equity injections needed to meet it, and short-term refinancings used to cure breaches, alongside the same narrowing bid-ask spreads that the price-discovery reading points to. The 2025 accounts sharpen it further: more than 100 investor and lender conversations found refinancing rising because lenders and borrowers had found ways to restructure and rebase values, while significant new transaction volume was still missing. This year's edition of the fair's own survey points the same way: of 430 exhibitors and visitors polled in August 2026, 40% call themselves cautious or very cautious about the market, up from 22% a year earlier, and 69% name capital availability as what the industry needs to become fit for the future. Attendees are thinking about money before they are thinking about price.
The 2026 backdrop keeps both readings alive at once. CBRE's lender survey found 72% of 134 respondents planning to increase 2026 origination, roughly €70bn of expected volume, evidence for a market with capital ready to price new deals, a signal explored on its own terms in The lender is also on a clock. The same survey found 66% of those lenders unwilling to lend against an asset that fails sustainability criteria without an improvement plan, which is exactly the condition that pushes a borrower toward a workout rather than a sale. Much of the non-bank money behind that appetite sits in closed-end debt funds with their own end dates, a second maturity calendar behind the borrowers' own, and the ECB raised rates by 25 bp at its 10 Sep meeting, effective 16 Sep: deposit rate 2.50%, main refinancing rate 2.65%, which moves the arithmetic against anyone refinancing a loan fixed before the reset. Every one of these figures supports both stories. JLL's own H1 2026 figures cut against the narrowing read from 2024: German volume ran 15% ahead of last year, but the asking-price gap between buyers and sellers widened rather than closed over the same stretch, evidence that runs in parallel through Germany is reopening by postcode, not by headline. The 2024 client-meeting anecdotes describe that year, not this one.
One fair-week disclosure shows the overlap inside a single transaction rather than across the aggregate evidence. A fair daily reported, during the 2025 edition, Target Healthcare REIT's agreed sale of nine UK care homes for £85.9m alongside a refinancing of £130m of banking facilities with a £70m accordion, disclosed together. The report does not say either was negotiated or signed inside the fair, which is exactly the gap at the centre of this whole argument: the evidence proves the two things happen in the same market and often the same week. It does not prove which one the fair itself produces.
What would actually settle it is not more sentiment data. It is an organiser-coded split of the programme between financing and acquisition content, which does not currently exist in a form a reader can use; a documented link between fair meetings and signed outcomes, which nobody publishes; and numbers from both sides of the table in the same week, a lender's live loan-to-value, a buyer's live entry yield, a seller's live reservation price. None of the public posts ahead of the 2026 edition states one of those three.
Our read: 2026 is still a refinancing fair with price discovery at the edges. What would prove us wrong is a named asset moving from guidance to a signed bid during the week. We will report it if it does.
What to test in Munich
- In a financing panel, listen for whether the number under discussion is a live loan-to-value or margin, or a general statement that lenders are "open".
- In an investment panel, listen for whether a speaker names an asset that moved from guidance to a signed bid, versus a general claim that "pricing has stabilised".
- Track how many sessions in the programme are framed around refinancing, NPLs or restructuring rather than acquisition, and compare that count with your own read of where the room's energy sits.
Sources
- Messe München, EXPO REAL 2024 final report, 9 October 2024
- EXPO REAL, 2025 final report, 8 October 2025
- CBRE Investment Management, EXPO REAL 2024 recap, 24 October 2024
- SitusAMC, What 100 Conversations at EXPO REAL Revealed About the CRE Finance Market, October 2025
- EXPO REAL Trend Index 2026, Real estate industry oscillating between caution and signs of recovery, 24 Sep 2026
- Real Asset Insight, EXPO Day October 2025, Day 2, 7 October 2025
- CBRE, European Lender Intentions Survey 2026, 16 Jun 2026
- ECB, Monetary policy decisions, 10 Sep 2026
- EXPO REAL, 2026 conference programme press release, 16 Sep 2026
- JLL, Germany Investment Market Overview Q2 2026, published 13 Aug 2026
 Germany is reopening by postcode, not by headline
 Czechia and Slovakia: whose money sets the price?
 Romania's yield premium: a reward for moving first or a warning?
 The new asset is not always a building
 Poland arrives city by city, not as one pavilion