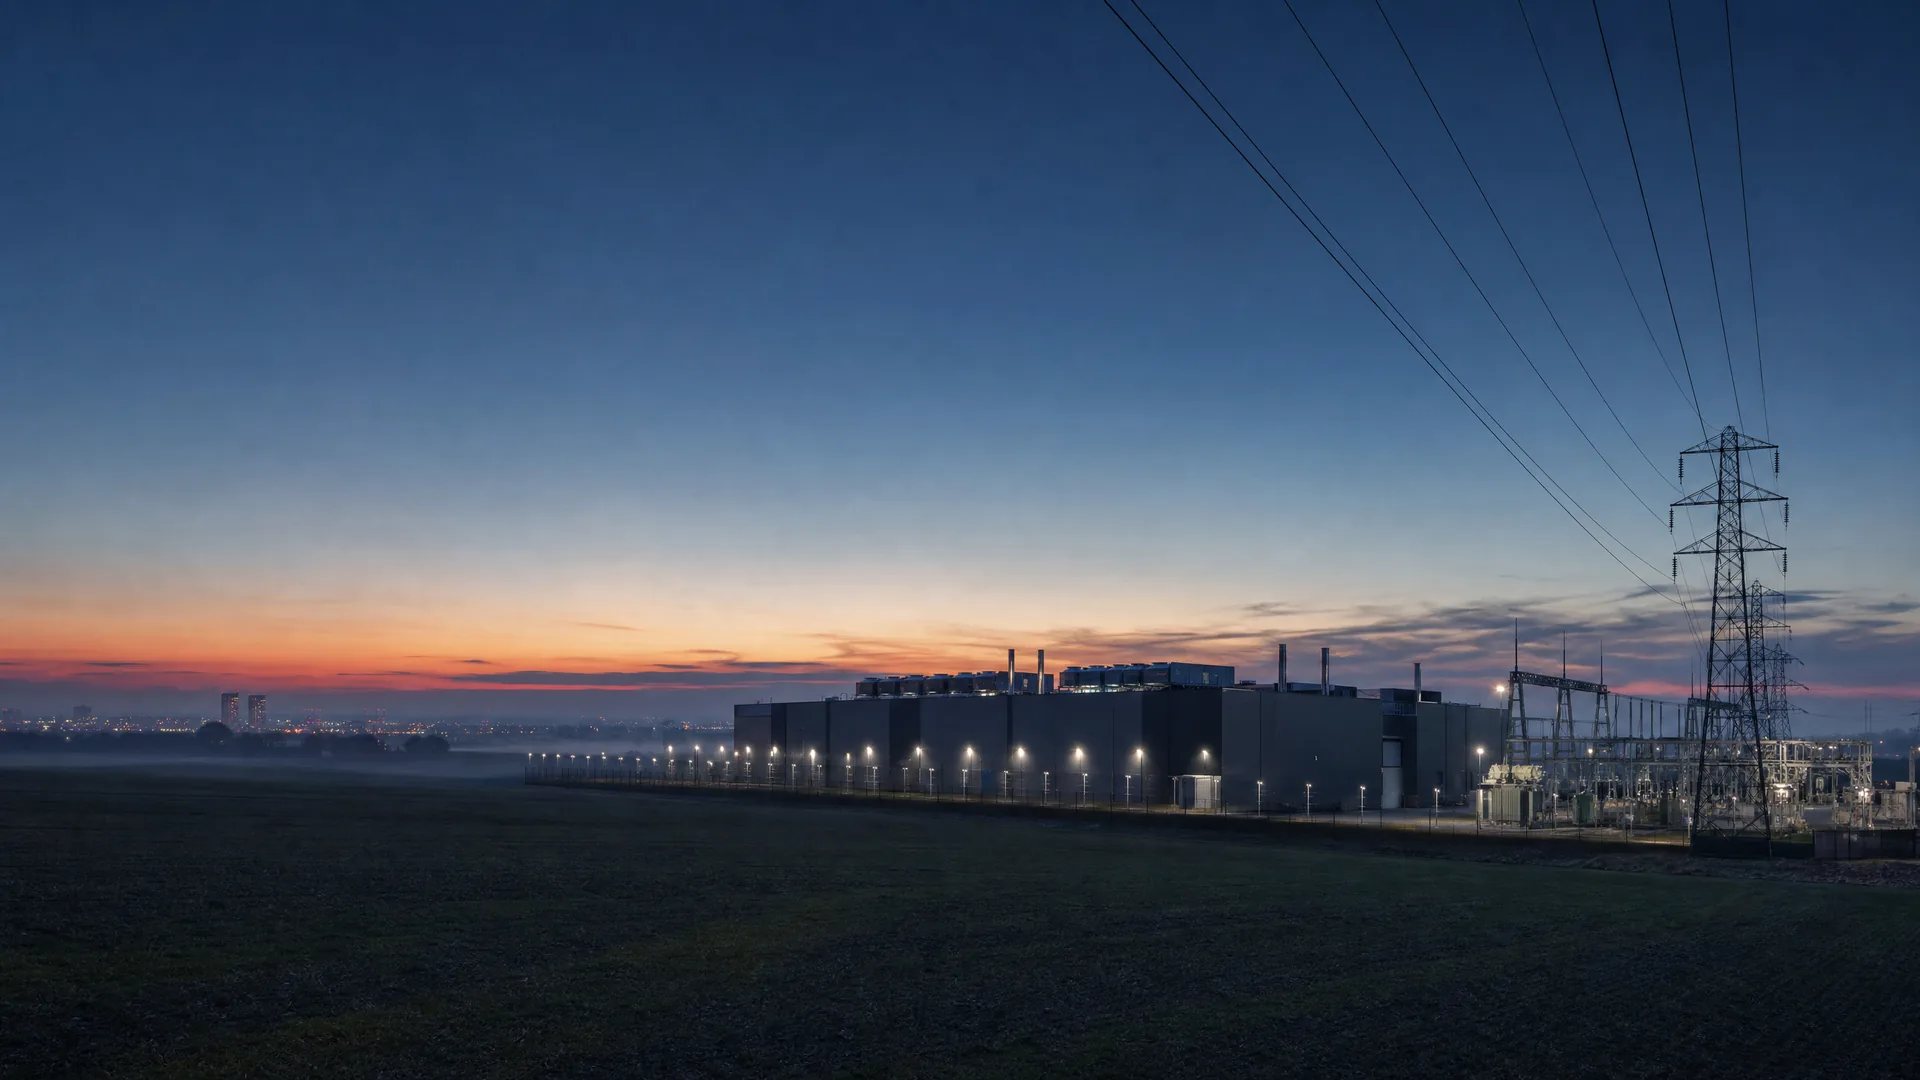
A developer who has spent two years securing planning consent for a data hall outside Frankfurt can still find, on the day she wants to build, that the harder permission was never the council's. It was the grid operator's. Her site can be zoned, financed and pre-let, and still sit empty because the connection queue has not reached her name. That inversion, a real estate constraint that lives upstream of real estate, is the premise behind the new InfrastructureNow forum on the 2026 EXPO REAL programme, and it is a genuinely new question for an audience used to thinking about planning consent as the main gate.
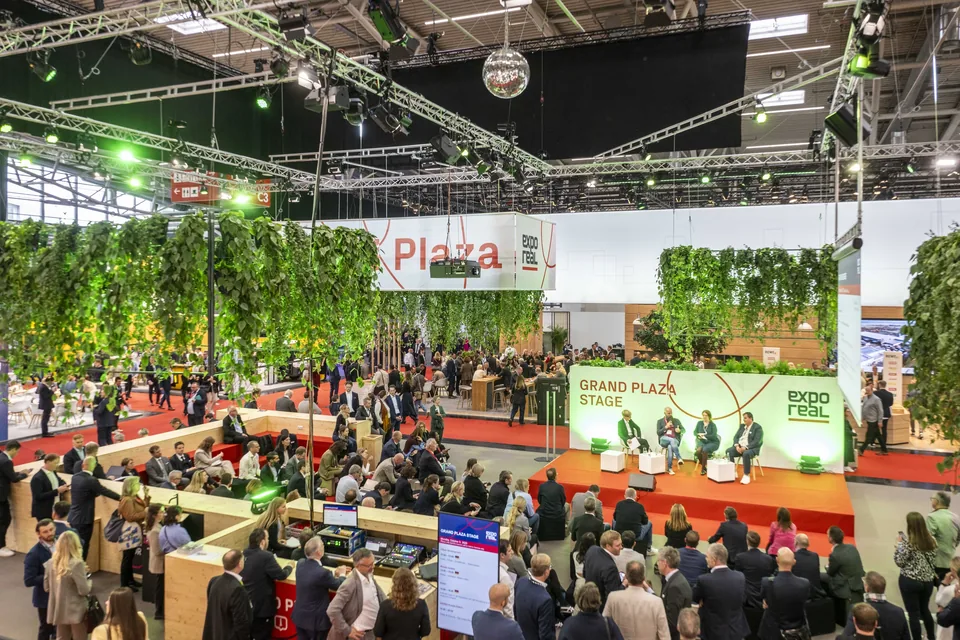
InfrastructureNow is the first dedicated platform at the fair for investable infrastructure: energy networks, digital infrastructure, social infrastructure and defence facilities, folded into a conference that has historically organised itself around buildings and sectors. The organiser's own framing treats infrastructure as an asset class alongside offices, logistics and living, rather than as a supporting utility for them. That framing matters because it changes what an investor should be underwriting. The traditional real estate checklist, location, tenant covenant, planning status, is necessary and no longer sufficient when the binding constraint sits in a grid operator's connection queue rather than a local authority's planning department.
Data centres make the case most concretely, because the numbers behind the sector are large and moving fast in both directions at once. CBRE forecasts European data-centre capacity will reach 13 GW by year-end 2026, a 20% rise on 2025, a figure that sits alongside the wider capital picture in What can actually get done in Munich? The organiser's own InfrastructureNow sessions are the fastest way to test that forecast against a named project this week. CBRE reports that new European colocation signings intended for AI more than quadrupled in the first half of the year. JLL's mid-year figures show why that demand is not translating into abundant available space: the five largest European hubs, Frankfurt, London, Amsterdam, Paris and Dublin, had colocation vacancy of just 6.4% in the second quarter, with Frankfurt at 3.1%. Partial pre-letting, once unusual, has become normal practice across the major markets, because tenants are securing capacity years before it is built.
The constraint behind that tightness is not land or capital. It is deliverable electricity. ENTSO-E expects European data-centre electricity demand to grow by more than 50% between 2025 and 2030, and in constrained areas it puts access-to-power queues at anywhere from several years to more than a decade. Ireland is the clearest documented case: EirGrid describes Greater Dublin as fully constrained, with 2 GW of data centres already contracted and market intelligence pointing to a further 6 GW of interest that the grid cannot currently accommodate. EirGrid's alternative, a conditional 150 MW to 300 MW around Galway, Limerick and Cork, is explicitly not secured capacity; it depends on individual technical assessment and, increasingly, on a project bringing its own linked generation or storage. A queue is not simply a delay in that system. It is a selection mechanism that rewards developers who can integrate power supply into a project rather than treat it as someone else's problem.
That mechanism is reshaping where capacity gets built, without making the established hubs irrelevant. JLL's pipeline data shows greenfield sites now make up 39% of projects in the 2026 to 2028 pipeline, against just 8% of what was delivered in the previous cycle, and the average distance of a new hyperscale site from a hub city has widened from 46 km for recently delivered projects to 175 km for the pipeline. JLL expects more than half of European AI-related growth to land in the Nordics and Tier 2 markets, where power is more available. The nuance an investor should hold onto is that this is workload-specific rather than wholesale: latency-sensitive applications still need to sit close to the established network-dense hubs, while power-hungry AI training campuses can move to wherever the electrons are. A portfolio built on the assumption that every workload is equally mobile will misread which sites actually hold pricing power.
The capital side of the story is still forming, and it is worth reading with its own caveat attached. EUDCA's State of European Data Centres forecasts €176bn of cumulative European new-construction investment for 2026 to 2031, capital that will land unevenly across the host country covered in Germany is reopening by postcode, not by headline and the CEE markets covered in Romania's yield premium: a reward for moving first or a warning? That is a construction-outlay estimate built partly on survey inputs where direct data are unavailable, not a comparable transaction-volume series, and it should not be read as a substitute for one. What it does establish is scale of intent: the capital lining up behind this asset class is being counted in the hundreds of billions, even before most of the grid capacity it depends on has been secured.
What to test in Munich
- At any InfrastructureNow or data-centre session, ask for the connection-offer status and expected energisation date behind a stated capacity figure, not just the demand forecast attached to it.
- Ask an operator whether a project's power supply is contracted, in queue, or still unaddressed, and who carries the risk if the timeline slips.
- Compare how a panel frames a "greenfield" or Tier 2 site: as a genuine relocation of demand, or as a specific, power-constrained response that leaves the established hubs' pricing power intact for latency-sensitive workloads.
Sources
- EXPO REAL, 2026 conference programme press release, published 16 Sep 2026
- CBRE, European Data Centres Figures Q2 2026, published 17 Aug 2026
- JLL, EMEA data centre mid-year 2026 report, published 3 Aug 2026
- ENTSO-E, Data centres and the power system, published May 2026
- EirGrid, Data Centre Connection Offer Process and Policy, Version 3, published 20 May 2026
- EUDCA, State of European Data Centres 2026, accessed 24 Sep 2026
 The lender is also on a clock
 The room can clear a price without closing a deal
 Czechia and Slovakia: whose money sets the price?
 Romania's yield premium: a reward for moving first or a warning?
 Poland arrives city by city, not as one pavilion