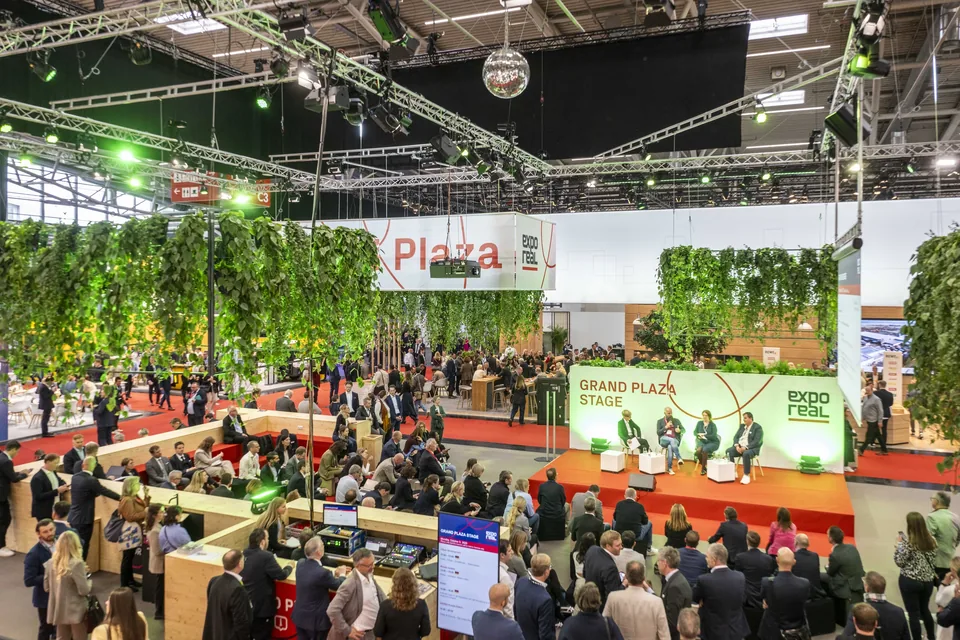
72% of 134 European lenders plan to lend more in 2026. Much of the newer, non-bank money sits in closed-end funds that have to hand capital back on a fixed date. Both facts describe the same market: more money wants in, and some of it is already on its own clock. A borrower walking into a German Sparkasse's stand this week with a straightforward question, will you refinance my loan and on what terms, is about to find out that the bank's answer depends on a sustainability screen, a rate that moved on 10 September, and banks that, by the ECB's own lending survey, were still tightening standards on enterprise loans in Q2. More capital wanting into this market does not make any one specific loan easier to place.
The scale of the appetite is not in dispute. CBRE's survey of 134 European lenders found 72% planning to increase 2026 origination, covering roughly €70bn of expected volume, with only 7% expecting to pull back. CBRE's midyear outlook, published in August, expects real estate credit to keep growing as an alternative asset class, with a rising number of non-bank lenders deploying capital allocated to it, and finds that competition between lenders kept margins tight in the first half even as the all-in cost of debt rose. Most of the lenders in CBRE's survey named refinancing as the main source of demand for loans, and CBRE finds terms still competitive for prime assets. On the headline numbers, this is a lender's market turning into a borrower's opportunity.
The condition attached to that capital is where the story turns. CBRE's same survey found 66% of respondents unwilling to lend against an asset that fails sustainability criteria without a credible improvement plan. That is not a blanket door closing; it is a sorting mechanism. An asset with a clean energy-performance certificate and a viable business plan now meets a genuinely larger pool of willing lenders than it did two years ago. An asset without one meets a smaller pool than the headline suggests: two in three of the same lenders will not write that loan without an improvement plan, so the new appetite flows almost entirely to assets that already qualify. The question is not whether capital exists. It is whether a specific asset, a specific borrower and a specific loan clear the underwriting bar that comes with it.
Two calendars complicate the picture further, and both are easy to miss from the borrower's side of the table. The first belongs to the debt funds themselves: most are closed-end vehicles with a fixed life, and a fund manager approaching the end of that life may prefer a shorter loan, an exit or a loan sale over a long-duration commitment, whatever the borrower needs. We have found no 2026 count of how much debt-fund equity reaches its end date in the next few years, which is why the question belongs on the fair floor. The second calendar belongs to the borrowers who are not refinancing yet, whose loans come due after the wave being discussed at this fair. We have found no maturity schedule for German or French real estate debt published this year that puts a euro figure, a loan-to-value or a sector breakdown on that later wave, so the borrower's side of the calendar is as hard to read from the fair floor as the lender's.
Rates are not standing still to make either calendar easier. The European Central Bank raised rates by 25 bp at its 10 Sep meeting, effective 16 Sep: deposit rate 2.50%, main refinancing rate 2.65%, up from a 2.00% deposit rate a year earlier, and a net 7% of euro-area banks were still tightening credit standards on enterprise loans in the second quarter, with risk perception and lower risk tolerance cited as the reasons. None of that is a commercial property lending series specifically. It is the backdrop against which every conversation on the fair floor about pricing and duration is happening this week, and it is the same backdrop The room can clear a price without closing a deal tests against a signed transaction rather than a stated intention.
Terms and timing are what the debt route through the programme is built to surface, session by session, rather than as a single aggregate appetite figure.
The interdependence between banks and debt funds is the part of the story that gets flattened most often into "banks retreat, funds fill the gap". They are not substitutes, and back leverage, debt funds borrowing from banks to expand their own lending capacity, is the reason. A back-levered debt fund writes its loans partly with a bank's money, so if the bank's own risk appetite tightens, the fund can be affected even where the underlying borrower's business has not changed. The ECB's May 2026 Financial Stability Review flags the same kind of link across private markets in general: euro area banks lend directly to private market funds, and although that lending is marginal, financing structures with multiple layers of leverage make the true level of risk hard to assess. Two lenders standing in the same hall this week may look like two separate sources of capital and still be exposed to the same upstream constraint.
What to test in Munich
- Ask any lender for the specific loan-to-value and margin they would write this week on a stabilised, sustainability-compliant asset, and compare it with what they would offer on one that is not.
- Ask a debt-fund representative whether their vehicle's own termination date is shaping what duration they are prepared to lend this year.
- In any NPL or refinancing session, listen for whether the panel names a euro figure or a loan-to-value for the "gap" it describes, or leaves the scale unstated.
Sources
- CBRE, European Lender Intentions Survey 2026, published 16 Jun 2026
- CBRE, European Real Estate Market Outlook Midyear Review 2026, capital markets, published 6 Aug 2026
- ECB, Financial Stability Review, May 2026, published 27 May 2026
- ECB, Monetary policy decisions, 10 Sep 2026
- ECB, Monetary policy decisions, 11 September 2025
- ECB, Euro area bank lending survey Q2 2026, published 21 Jul 2026
- EXPO REAL, 2026 conference programme press release, 16 Sep 2026
 The room can clear a price without closing a deal
 Germany is reopening by postcode, not by headline
 Czechia and Slovakia: whose money sets the price?
 Romania's yield premium: a reward for moving first or a warning?
 Poland arrives city by city, not as one pavilion