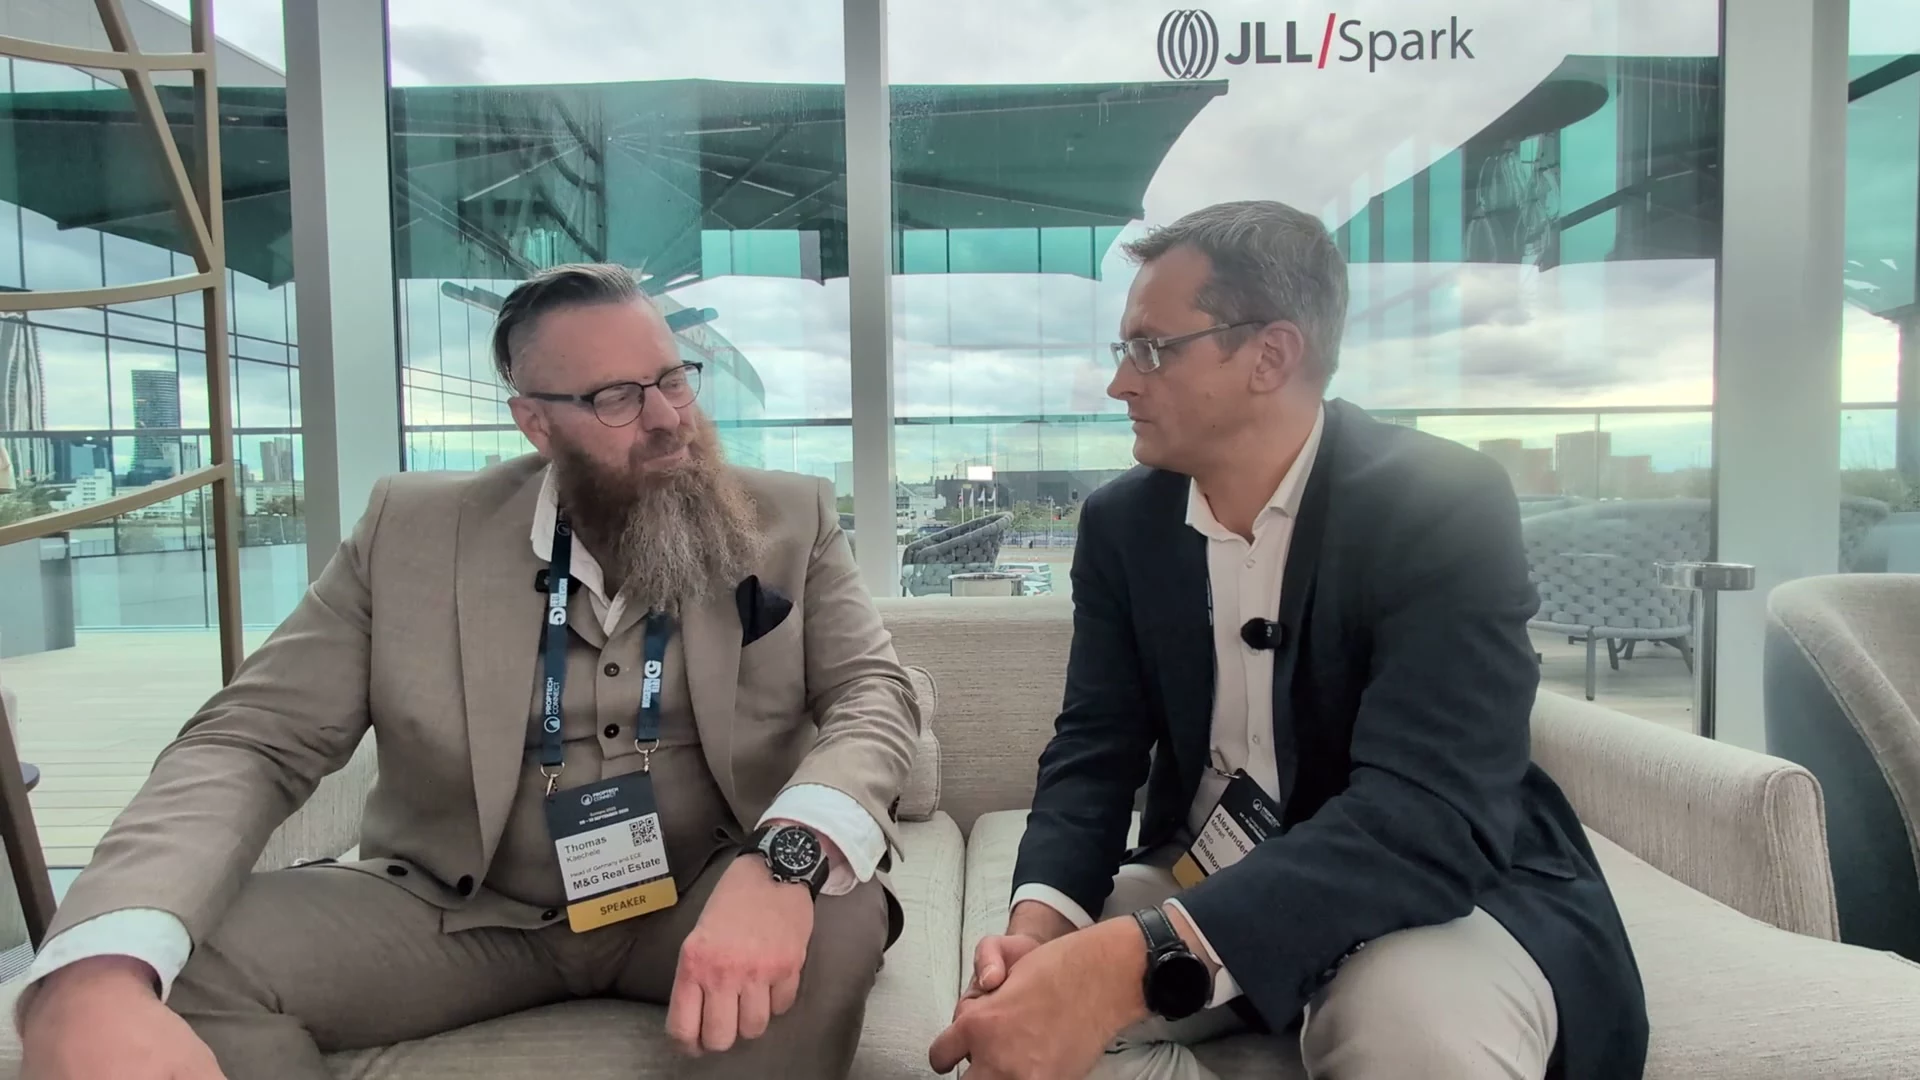
Tom Walker co-heads global listed real assets at Schroders, so he buys the companies that own the buildings rather than the buildings themselves. He spoke with Alexander Morari, MRICS, CEO of Shelton Reed, on the second day of PropTech Connect Europe 2026 at the InterContinental London, The O2, for eleven minutes on where the listed market is working.
Key takeaway: the earnings are in America, prime assets are not overvalued because they can still grow rents faster than debt is repricing, and the technology on show helps the operators Walker invests in, not the way he invests.
Where the strength is
Walker opened with a geography, not a sector. On his read, the public market’s momentum has sat in one place for years, with Asia behind it and Europe trailing both.
It’s pretty clear, both on a year-to-date basis as well as over the last two or three years, that the strength in the public markets for real estate is over in the U.S. Asia is probably coming second, and then Europe is certainly lagging... I would highlight three in particular. Firstly, it would be data centres. Secondly, it would be senior housing. And then thirdly, it would be retail. Tom Walker, Schroders
Those three, he said, are producing some of the strongest earnings he has seen so far this year.
Retail, rebuilt by attrition
Asked whether retail is genuinely back, Walker said yes, and explained it as a survivors’ story. Ten to fifteen years of falling values, falling rents and supply leaving the market have left a small group of dominant owners holding high quality assets serving very large catchment areas. Those owners, he argued, can now drive rents and face little competition. He sees the same effect in grocery anchored retail.
Morari pressed him on whether a flight to quality simply means paying up for assets that are already richly valued. Walker rejected the framing.
I wouldn’t look at it that the prime assets are overvalued. We think that the prime assets actually offer investors much more resilience, and we think that earnings, i.e. rental growth, can continue to grow because there’s a lack of competition. Tom Walker, Schroders
The test he set out is relative. Cost of capital is rising globally and sovereign yields are backing out, so an asset has to grow earnings faster than its cost of debt is increasing. Prime assets, in his view, can solve for that.
Data centres, with the risk acknowledged
Morari put the sharpest question of the interview. If Asian and Chinese open source models can be produced at a fraction of the cost and reach most of the performance of the closed systems, does that disrupt the data centre trade? Walker did not deflect it.
We absolutely kind of see it as a threat... whatever that risk is, whatever that threat is, the demand for data centers continues to grow, and there’s a finite source of data centers, and so earnings are growing fast... at the moment we think those risks are balanced, and that the rewards are greater than those risks from a risk-adjusted basis. Tom Walker, Schroders
He has invested in the sector for more than ten years, he said, and there has always been a threat of some kind. He named rising hyperscaler debt as another live one.
What he buys inside the sector is narrower than the headline. Walker said he focuses on cities because they are high barrier to entry markets where building is very hard, which means the data housed there tends to matter. He is not interested in a facility in the middle of nowhere storing photographs taken three years ago. He wants low latency data, trading news and online gaming among his examples, and said the binding constraint in Frankfurt, London, Amsterdam and Paris is buildability.
What the floor is worth to an investor
On the exhibition halls, Walker drew a clean line. Most of the disruption he saw, he said, is aimed at building owners, operators and asset managers. He buys companies rather than operating assets, so he does not expect it to disrupt his own discipline.
That does not make it irrelevant to him. He said new technology is advantageous for the companies he invests in, and that he would expect their operating margins to improve. He was more sceptical about the supply of vendors than the demand, noting how many firms appeared to be selling arguably the same building management systems, and expecting one or two leaders rather than the dozens on show. Morari added the interoperability problem, that solutions bought across a building’s lifecycle often do not talk to each other, and Walker agreed.
Asked what those companies should do to win, his answer was brief.
You’ve got to scale quickly. You’ve got to build the relationships with the largest owners and enjoy those economies of scale. Tom Walker, Schroders
What to watch
Walker’s framework gives three things to track rather than three predictions. Whether prime rental growth keeps outrunning the rising cost of debt, since that is the test he set. Whether the risk balance he described in data centres holds as hyperscaler leverage builds. And whether the building management market consolidates towards the few leaders he expects, which is where the margin improvement he is underwriting would appear.
Watch the interview.