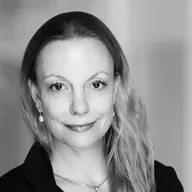
Dina Lorentz is Managing Director (Geschäftsführerin) of the Bundesverband Impact Investing e.V. (BVII), the federal association for impact investing in the DACH region. She spoke with Alexander Morari, MRICS, CEO of Shelton Reed, at EXPO REAL 2026 in Munich for sixteen minutes, and her answer to "what counts as impact?" kept coming back to one test: measure the effect on the people the asset is meant to serve.
Key takeaway: impact investing is a financial return plus a social or environmental outcome with a demonstrable link between the two, "affordable" has to be checked against tenants' incomes rather than a discount to market rent, and affordable housing usually needs a public component to work for investors.
What is impact investing, and how is it different from ESG?
Lorentz started with the definition. An investment qualifies when the investor intends to reach a specific outcome through the asset, and when that outcome can be tied to the capital deployed.
The combination, financial return plus an impact and the causality between the two, that's what makes an impact investing, basically speaking.
Dina Lorentz, BVII [03:09]
Morari wondered whether this is a diplomatic way of giving up return. Lorentz said that debate is ongoing, but in her account risk is not blended out: the investor looks for an additional return and an effect on something like affordable housing, holds the asset with a long-term view and works with it actively.
BVII has made recommendations on the EU's sustainable finance disclosure rules, which the European Commission proposed to revise on 2025-11-20. She said the association gives recommendations rather than demands, including on SFDR 2.0, to make the line clear between sustainable investing, ESG and impact. What sets impact apart, in her words, is a defined process.
...you are able to track and evaluate something more that goes beyond its mere financial return and a short term vision. And this kind of process and the KPIs you're setting, the theory of change.
Dina Lorentz, BVII [06:10]
Why do institutional investors rarely say they do impact investing?
Morari raised the question of whether impact is a side activity of large developers or someone's only model. Lorentz said most BVII members are stricter impact investors, and that the association wants to reach more institutional capital. Its survey this year, she said, found that outreach to institutions is very low.
According to the survey, the outreach to institutional investors is very low. And that does not mean necessarily that institutional investors do not follow an impact investing approach. Many do actually.
Dina Lorentz, BVII [06:53]
The gap, as she described it, is about labels. German and some other European investors would rather not state publicly that they follow impact rules in the strict sense, partly for reputational reasons and partly because impact investing is not anchored in a hard regulatory definition. Many of them still track KPIs on both sides: the effect of their capital on the asset, and the effect of the asset itself. An insurer, she said, would not claim to do 100% impact investing under the more robust framework BVII applies.
Is a rent 10% below market affordable housing?
Morari tested the boundary with a modern art museum in a residential district. Lorentz agreed that neighbours benefit, and widened the point.
Every investment creates an impact.
Dina Lorentz, BVII [09:17]
For context, Destatis counted 206,600 dwellings completed in Germany in 2025, down 18.0% on 2024. Her example was an investor who offers housing 10% below market rent and calls it affordable. The test she described is to look at the tenants: their income, weighed against what the rent costs them.
Usually you come to that, oh, well, actually it's not affordable at all. You are not providing affordable housing to low income people.
Dina Lorentz, BVII [09:17]
She applied the same discipline to a social housing fund for seven CEE countries that she advised. The objective, affordable homes for low-income people, families, students and homeless people, cannot be set once for the whole region. Each country needs its own look at average household incomes, so economic data decides what "affordable" means in that market.
Why does affordable housing need public money?
Lorentz described a second tension inside mixed schemes. If a project adds luxury apartments on the upper floors, say 20%, with the rest for lower-income tenants, to reach a market-rate return, the requirements and expectations of the luxury buyers, who do not want to live alongside lower-income tenants, clash with the rest of the scheme. That, she said, is why public support is usually part of the structure.
That's why exactly in affordable housing you need usually public components to support a market rate return and make it attractive for investors.
Dina Lorentz, BVII [09:17]
Morari checked whether she meant subsidies. She said yes, in many cases, especially at the start when the building is being built. After that come the rental payments and the infrastructure around the building, which is where she widened the view.
She also argued for judging the scheme as an ecosystem. In her account, a place with a childcare centre, a bakery and a doctor nearby creates a better living environment, and multi-generational homes lift the education level of the children who grow up in them. Affordable housing, in that view, delivers more than the rental yield alone.
Who is in the association, and what is next?
BVII has around 135 members, Lorentz said, from across the impact investing ecosystem and not only real estate: investors, financial institutions, insurers and foundations. It is DACH-based, and she said the aim is to open up to Europe, since the regulation and the finance ecosystem are European.
On what a good end of 2026 looks like, she pointed to work with public authorities on making climate adaptation in communal streets in cities such as Berlin financeable for the residents themselves, beyond a bank loan, through a financial vehicle they can invest in. The principle she stressed:
We need new financial vehicles that every part of the society can take part and participate in and get a return out from that.
Dina Lorentz, BVII [14:49]
What to watch
Lorentz's framework gives three things to track rather than three predictions.
- Definitions. Whether the line between ESG and impact, which BVII addressed in its SFDR 2.0 recommendations, stays clear enough for investors to point to a process rather than a label.
- Institutions. Whether institutional investors that already track impact KPIs begin to say so publicly, which is the gap BVII's survey describes.
- Affordability tests. Whether housing schemes set "affordable" against local household incomes, as in her CEE fund example, and whether public components are agreed at the start of a project.
FAQ
What is impact investing in real estate?
Dina Lorentz defines it as an investment with a financial return combined with a social or environmental outcome, where the investor intends the outcome and the link between the capital and the result can be shown.
Does impact investing mean accepting a lower return?
Lorentz said it is an ongoing debate. Her position was that the risk side is not ignored, and that the investor seeks a return plus an impact, usually over a longer holding period and with active work on the asset.
How should investors test whether housing is affordable?
By looking at the tenants. Lorentz said to weigh their income against the rent, and in a multi-country fund to use the average household income of each country rather than one objective for all.
Why does affordable housing often need public support?
In her account, a market-rate return and a low-income tenant base pull in different directions, so a public component, including subsidy at the start of a build, is usually needed to make the scheme attractive for investors.
Who are BVII's members?
Around 135, according to Lorentz, including investors, financial institutions, insurance companies and foundations, mostly in the DACH region, with an aim to open up to Europe.
Watch the PeerView.