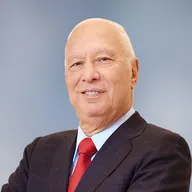
Chaim Katzman is the founder of G City, which he describes as an owner and operator of shopping centres in major cities from São Paulo to Miami, New York, the Nordics, Warsaw and Tel Aviv. He spoke with Alexander Morari, MRICS, CEO of Shelton Reed, at EXPO REAL 2026 for nineteen minutes, and his thesis is that the mood around retail property swung hard for 20 or 30 years while occupancy and income held steady, so G City is concentrating on fewer, bigger, better located assets, with Warsaw at the centre.
Key takeaway:
Katzman's case rests on four points:
- Retail reality stayed stable while perception lurched.
- Scale and location beat store count.
- Residential density on land G City already owns is the growth route in Poland.
- Warsaw is more likely than Prague to become an East Berlin.
Has retail really changed, or only the mood around it?
Morari opened on retail's health after several crises. Katzman's answer was that the assets barely changed, and the perception of them did.
The interesting thing about retail assets in the last 20 or 30 years is that not much changed in the assets. What did change was the perception about these assets.
Chaim Katzman, G City [01:33]
He walked through the swings as he saw them. Shopping centres sold cheaply in the United States in the late 1980s, then Western developers built the first generation in Poland, Romania and the Czech Republic after communism. The 2000s made them the darling of the industry, e-commerce and the pandemic brought predictions of their demise, and inflation brought doubts about buying them at all. His counter was the operating record.
Throughout all these ups and downs, shopping centers were 95% filled, NOI was paid on time, there was NOI growth, 2%, 3%.
Chaim Katzman, G City [01:33]
NOI is net operating income, the rent left after running costs. His reading is that the visit pattern is the stable part: people shop for food on the way home from work, and while there they add coffee, a daycare drop-off or the gym. Tenants change, he said, but a centre in a desirable area has not changed much in 25 years. He came back to the point a minute later, with advice about location on the commute.
So you should be on the going home side of the track.
Chaim Katzman, G City [05:17]
Why did G City move from hundreds of small centres to dozens of big ones?
Morari turned to the portfolio upgrade. Katzman described a deliberate trade of count for size.
We moved from over 400 shopping centers to the tune of $10 billion to 80 shopping centers with the same amount of dollars.
Chaim Katzman, G City [06:06]
The average asset, by his figures, went from about $25 million to more than $100 million, because management attention goes further on larger centres and there is more opportunity inside them. He called the flight to quality in retail "location", sometimes a good tenant mix and a link with the local community, and tied the two together.
Location begets the valuable retailers. They don't want to go to places where they don't have any footfall.
Chaim Katzman, G City [06:06]
Is residential becoming a second business line?
Morari pointed to residential projects in Warsaw, next to the Promenada centre and on land at Ostrobramska, and to a development in Tampa called AER, short for Arts and Entertainment Residences. Katzman named Promenada as the blueprint: excess land was developed, which added the density a successful centre and neighbourhood need. He added an ESG argument, that people use cars less when what they need sits across from where they live.
He was clear about the limits of the model in Poland. He does not expect to put up a large residential estate from nowhere. What he described instead:
But you will find us creating more density in our existing shopping centers, intensifying our uses to develop more residential, to take better advantage of the infrastructure that's already been built.
Chaim Katzman, G City [08:25]
On whether the Ostrobramska land was repurposed, he said some of it was. G City is building another thousand or so apartments there, he said, and has a few more projects in the pipeline, not all of them in Poland.
Why Warsaw, and not Prague?
G City Europe sold its Czech centre, Atrium Flora in Prague, in February 2025, and Katzman said the aim was to focus on Poland. Katzman gave the city case in his own numbers: Warsaw has two million citizens but a metropolitan area of four million, 300,000 students and four million tourists, and Poland sits in the middle of Europe on the map. His comparison with Prague was direct.
So while Prague is a great city and we love Prague, we still think that the greater chances are that Warsaw will become an East Berlin, not Prague.
Chaim Katzman, G City [10:16]
Morari, who is based in Poland, agreed that the country keeps delivering for investors and raised the question of what Warsaw needs to get there. Katzman did not frame it as a race with Berlin. He framed it as accumulation: more businesses, jobs, students and investors. Then he gave the portfolio evidence.
Look, from our little portfolio we saw growth that is outperforming any other place. I mean, we saw almost 16% same-store NOI growth, which is huge by our standards. And we do not see it abating.
Chaim Katzman, G City [11:54]
He said 2027 would probably bring double digits again, credits a consumer who is willing to buy, and sees government policy helping that consumer buy an apartment and then spend. His summary of the base is the growth of the middle class in Warsaw, which he called the bedrock of a healthy metropolis.
The company's own filings point the same way. G City Europe's 2025 statements describe a plan to reposition its retail portfolio to prime Warsaw assets and grow residential for rent, and the same statements record that the sale of three centres outside Warsaw, for an agreed gross property value of EUR 455.8 million, completed on 2 December 2025. The centres were:
What is the plan for the balance sheet and the pipeline?
Morari brought up deleveraging. Katzman recast it as focus. G City, he said, has divested non-core assets outside its chosen markets, keeps some of them under management, is selling a few assets in Brazil, and has taken the Nordic company Citycon almost completely private. After a second tender offer for all remaining shares, G City held about 91.05 percent of Citycon at the end of August 2026 and began compulsory redemption of the rest.
We are focusing on our core portfolio, and our core portfolio is what we own in Warsaw, what we own in several Nordic countries, what we own in the US and Israel.
Chaim Katzman, G City [14:25]
The development rights inside those assets are the next phase, as he listed them:
- Promenada in Warsaw: about 6,000 square metres being built now, followed by about 22,000 square metres that he expects to start sometime in 2027. G City Europe confirmed the construction start of the first phase in June 2026.
- Israel: about 60,000 square metres of office in one property.
- Miami: another residential building on land G City already owns.
What should we expect by the end of 2027?
Morari wondered what would surprise people about G City by end-2027. Katzman said more growth in Central Europe, predominantly Poland. On the Nordics he described a portfolio of 26 assets in which 12 make up 80 percent of the portfolio, with time spent on the other group, and said that will change. He believes G City brings a different approach to property and asset management there, and that going private lets it lift performance and cut expenses.
Morari closed by saying he hoped to meet again and check the result. Katzman answered with the line of the PeerView.
Well, we don't make any promises, but we deliver.
Chaim Katzman, G City [19:05]
What to watch
Katzman's own claims give three things to track rather than three predictions:
- Whether Warsaw same-store NOI growth stays in double digits in 2027, the figure he said he does not see abating.
- Whether the Promenada extensions and the Ostrobramska apartments reach the starts and deliveries he described.
- Whether the Nordic portfolio is reshaped around its biggest assets after the Citycon take-private.
FAQ
What is G City's strategy in Poland?
Katzman said G City sold its Czech holding to focus on Poland, and that growth there comes from densifying existing centres with more retail and residential rather than building large residential estates from scratch.
Why does Katzman think retail property has held up?
He argues the assets themselves barely changed over 25 years, with occupancy near 95 percent and steady NOI growth, while the market mood moved with each wave of worry. In his view people's shopping habits change more slowly than sentiment does.
What did G City do with its portfolio?
Katzman said it moved from over 400 centres worth about $10 billion to 80 centres of the same total value, raising the average asset from about $25 million to more than $100 million.
Watch the PeerView.